
Could a journey from Vienna require Slovenian VAT accounting even when Slovenia is only one part of the route? For coach operators, the answer depends on the transport service and route, not just the departure point. The customer, contract and operator’s business details also matter. For Coach Ltd., start by assessing the service actually supplied rather than assuming that every cross-border journey follows the same VAT treatment. This is relevant to coach businesses operating routes into Slovenia.
You may be unsure which business information and records to prepare, or whether a special VAT procedure for occasional international passenger transport could be relevant. This article explains the facts that shape an assessment, what to organise before discussing your accounting, and how TaxSlovenia’s Slovenian VAT registration and accounting support can help you identify practical next steps.
Key Takeaways
- Assess your company’s circumstances alongside the route and type of passenger transport before drawing conclusions about Slovenian VAT.
- For Coach Ltd., prepare company and journey details to make your VAT discussion more focused.
- Gather relevant invoices, contracts and existing VAT records to help organise the accounting review.
- TaxSlovenia provides VAT registration, accounting and a special VAT procedure for bus companies to support your next steps.
Slovenian VAT for coach passenger transport: what UK operators need to assess
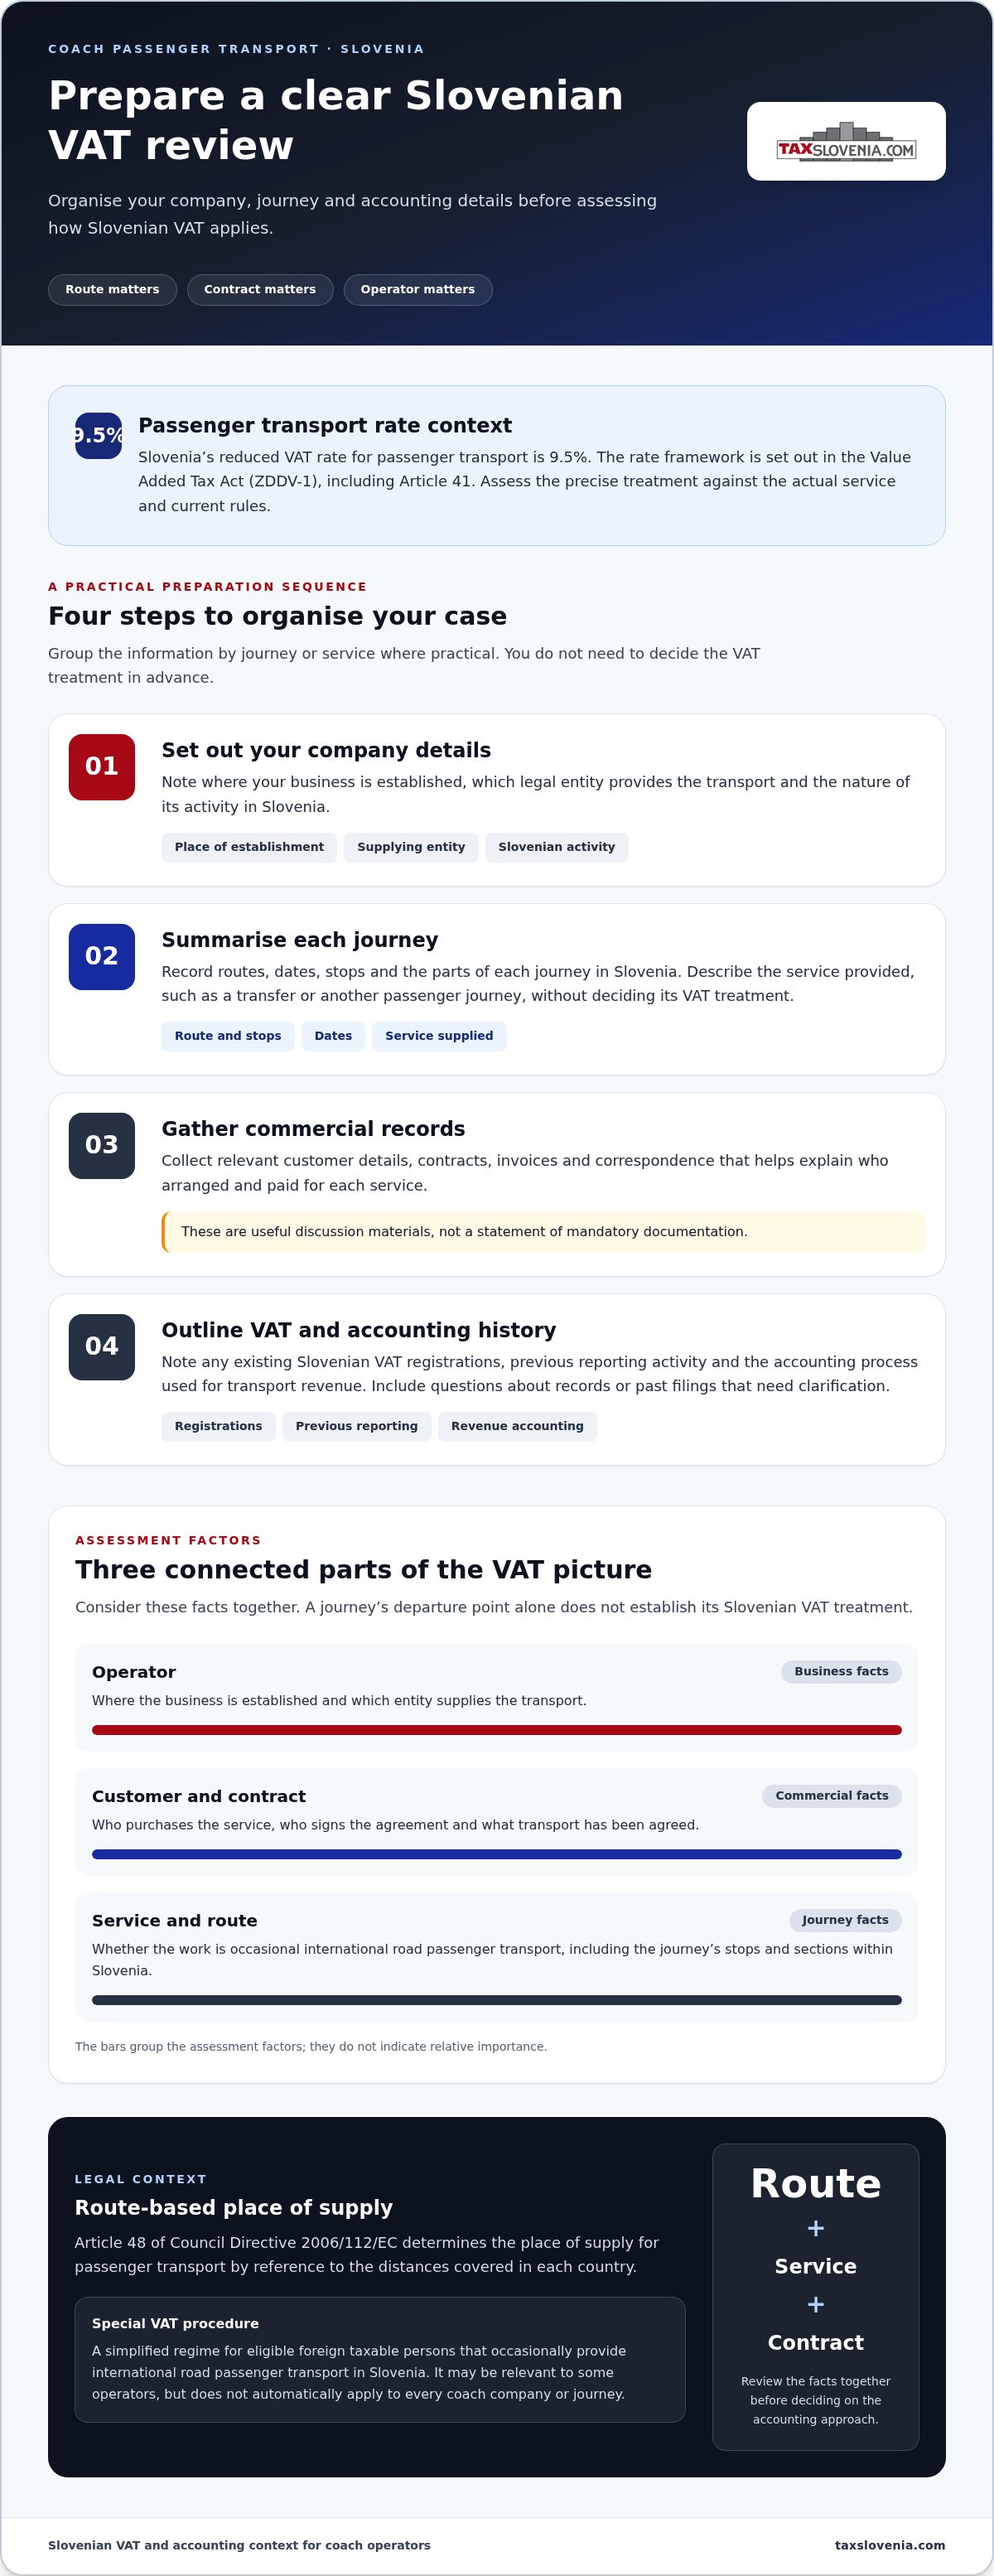
The VAT assessment depends on the operator and the transport facts. A journey starting in Vienna may cross several borders, but its departure point alone does not establish how the service should be treated in Slovenia. The route, the service supplied, the customer and the contractual arrangements all help define the transaction. For cross-border passenger transport, Article 48 of Council Directive 2006/112/EC provides that the place of supply is determined by reference to the distances covered in each country.
Slovenia’s reduced VAT rate for passenger transport is 9.5%, as stated in the current Slovenian VAT guidance. The rate framework is set out in Slovenia’s Value Added Tax Act (ZDDV-1), including Article 41 and its provisions on reduced rates. Assess the precise treatment against the actual service and current rules. The Transport in Slovenia overview provides general context on the country’s transport network, including bus services, but it is not a source for determining your VAT position.
Which facts can affect a Slovenian VAT assessment?
Keep the commercial details and journey information distinct. Consider them together to give your adviser a clear basis for reviewing the transaction without presuming its tax result:
- Operator: where your business is established and which entity supplies the transport.
- Customer and contract: who purchases the service, who signs the agreement and what transport has been agreed.
- Service and route: whether the work is occasional international road passenger transport, and the journey’s stops and sections within Slovenia.
A special VAT procedure is a simplified regime for eligible foreign taxable persons that occasionally provide international road passenger transport in Slovenia. It may be relevant to some operators, but it does not automatically apply to every coach company or journey. For Coach Ltd., the operator, contract and route facts should be assessed before deciding on an accounting approach.
How UK coach companies can prepare for Slovenian VAT accounting support
A clear summary of your business and Slovenian transport activity makes an accounting discussion more focused. You do not need to decide in advance which VAT treatment applies or assume that a particular document is compulsory. Start with information you already hold, then identify gaps and questions for review.
What information should you organise before discussing your case?
Work through these steps in order. Where practical, group records by journey or service so the relevant details are easier to compare.
- Set out your company details. Note where the business is established, which legal entity provides the transport and the nature of its activity in Slovenia.
- Summarise the journeys. Record routes, dates, stops and the parts of each journey in Slovenia. Describe the service provided, such as a transfer or another passenger journey, without deciding the VAT treatment in advance.
- Gather commercial records. Collect relevant customer details, contracts, invoices and correspondence that helps explain who arranged and paid for each service. These are useful discussion materials, not a statement of mandatory documentation.
- Outline your VAT and accounting history. Note any existing Slovenian VAT registrations, previous reporting activity and the accounting process used for transport revenue. Include questions about records or past filings that need clarification.
For current Slovenian tax policy context, consult the Slovenian Ministry of Finance Tax Directorate. Your company’s circumstances and records need to be considered together when assessing the accounting approach. This preparation gives Coach Ltd. a practical starting point: present your company, journeys and existing processes clearly.
TaxSlovenia provides support with Slovenian VAT accounting questions. Use the contact form to outline your company’s situation and the support you need.
How TaxSlovenia supports Slovenian VAT and accounting for bus companies
For an international coach operator, Slovenian VAT questions should be approached through the company’s actual activities and records. TaxSlovenia provides business tax advice, accounting services and VAT registration support, including a special VAT procedure for bus companies. This Slovenian support helps you organise the relevant issues without assuming that one procedure or tax outcome applies to every operator.
What to expect when discussing your company’s requirements
An adviser can review your business circumstances and transport information, then discuss the accounting support relevant to your needs. Organised company and route details help frame that discussion. They show how your Slovenian activity fits with your existing accounting processes and which points need attention. This assessment is particularly relevant when considering the bus-company procedure, as its suitability depends on the operator’s circumstances.
TaxSlovenia’s support covers VAT registration, business accounting and the special procedure for bus companies. These are distinct services, and the right scope depends on your requirements. TaxSlovenia works with Slovenian and international businesses, helping you address local VAT and accounting questions in context. For an overview of the available service areas and fee information, see TaxSlovenia’s services and fees.
For Coach Ltd., explain your company’s Slovenian transport activity, the accounting questions you need to resolve and the relevant records you hold. Contact TaxSlovenia through the contact form to outline your Slovenian VAT and accounting needs and discuss support suited to your circumstances.
Set a clear course for your Slovenian VAT arrangements
As your routes and transport services develop, keep records that connect each journey with its customer and agreed service. This gives you a practical basis for reviewing future activity and discussing changes in your Slovenian VAT accounting. For Coach Ltd., a focused review of your circumstances can help you identify the questions to address.
TaxSlovenia supports international businesses with VAT registration and accounting, as well as a special VAT procedure for bus companies. The procedure’s relevance depends on your circumstances, so discuss your requirements before deciding how to proceed.
Set out your company’s needs and take the next step with informed support from TaxSlovenia.
Disclaimer
The information provided in this article is for general informational purposes only and does not constitute tax, legal, accounting or other professional advice. Tax treatment may vary depending on the specific facts and circumstances, and legislation and administrative practice may change over time. Before making any decision or taking any action based on this information, we recommend obtaining professional advice tailored to your individual circumstances.


