
A Buchhaltungsübernahme d.o.o. Slowenien unterjähriger Wechsel für Konzerne aus Stuttgart is more than a change of provider: it is a controlled handover of accounting records and responsibilities. If your group is based in Stuttgart, Munich, Vienna or elsewhere in Germany, Austria or Switzerland and has a Slovenian subsidiary, you need a clear cutover plan that supports both local bookkeeping and group reporting. Mid-year, the key questions often concern balances, VAT, payroll information and work still in progress.
A sequenced handover gives you an agreed transition point and a practical way to maintain continuity between Slovenian accounting records and group reports. This guide explains how to coordinate the outgoing and incoming teams, transfer records and align ongoing bookkeeping, tax and payroll information with your group’s finance processes. Use it to identify what to settle before the change, during the transfer and once the new arrangement begins.
Key Takeaways
- A mid-year provider change can preserve year-to-date information when you first define the reporting needs, responsibilities and reason for the change.
- Set a clear cutover scope for a Buchhaltungsübernahme d.o.o. Slowenien unterjähriger Wechsel für Konzerne aus Stuttgart, covering balances, transaction details, supporting documents and open items.
- Reconcile transferred data before relying on it for ongoing Slovenian bookkeeping, tax and payroll work.
- Agree how local accounting outputs will meet your Stuttgart group’s reporting timetable and internal processes, including any requirements from finance teams in Germany, Austria or Switzerland.
Why a Stuttgart group may change bookkeeping for its Slovenian d.o.o. mid-year
Changing bookkeeping providers during the financial year does not have to mean losing control of the records already created. For a group with finance stakeholders in Stuttgart, Munich, Vienna or Switzerland and a Slovenian subsidiary, a defined transition can preserve the accounting trail and establish who is responsible for each task from the cutover date. Common reasons include changing reporting needs, a mismatch between the service and the company’s requirements, or difficulties coordinating information across entities.
The Slovenian subsidiary’s local bookkeeping and the group’s internal reporting are connected, but they serve different purposes. Local records support the company’s accounting and tax processes in Slovenia. Group reporting may require additional classifications, deadlines or management information. Agree how the two sets of outputs relate, and do not treat a group reporting pack as a substitute for local records. A d.o.o. is a Slovenian limited-liability company; the general Limited Liability Company (LLC) structure offers background on this type of business entity.
A Buchhaltungsübernahme d.o.o. Slowenien unterjähriger Wechsel für Konzerne aus Stuttgart should start with decisions about governance and reporting, not only the date when one provider stops and another begins. This is especially useful when the subsidiary’s finance contacts and the group team are working across borders, such as between Slovenia, Germany, Austria and Switzerland.
What the group should agree before setting a cutover date
Identify who approves the change, who holds the relevant records in Slovenia and which group finance stakeholders need to receive or review reports. Then list the outputs, periods and responsibilities the handover must cover. For example, decide whether the incoming team needs to continue bookkeeping from a particular month, complete work already underway, or prepare information for a group reporting deadline.
- Specify the periods and reporting outputs included in the handover.
- Assign an owner for outstanding questions and coordination between the outgoing team, incoming team and group finance.
- List VAT, payroll and annual-account work in progress, along with its status and next action.
Use this list to choose a cutover date that fits the work in progress. Review VAT, payroll and annual-account responsibilities against the d.o.o.’s circumstances rather than assuming that the same timetable or process applies to every subsidiary.
How to manage the mid-year bookkeeping handover for a Slovenian d.o.o.
For a group whose finance team is in Stuttgart, Munich, Vienna or Switzerland, the handover must connect the Slovenian subsidiary’s accounting information with the parent company’s reporting process. Define what the group needs and how it will use that information, while keeping local records distinct from internal group reports.
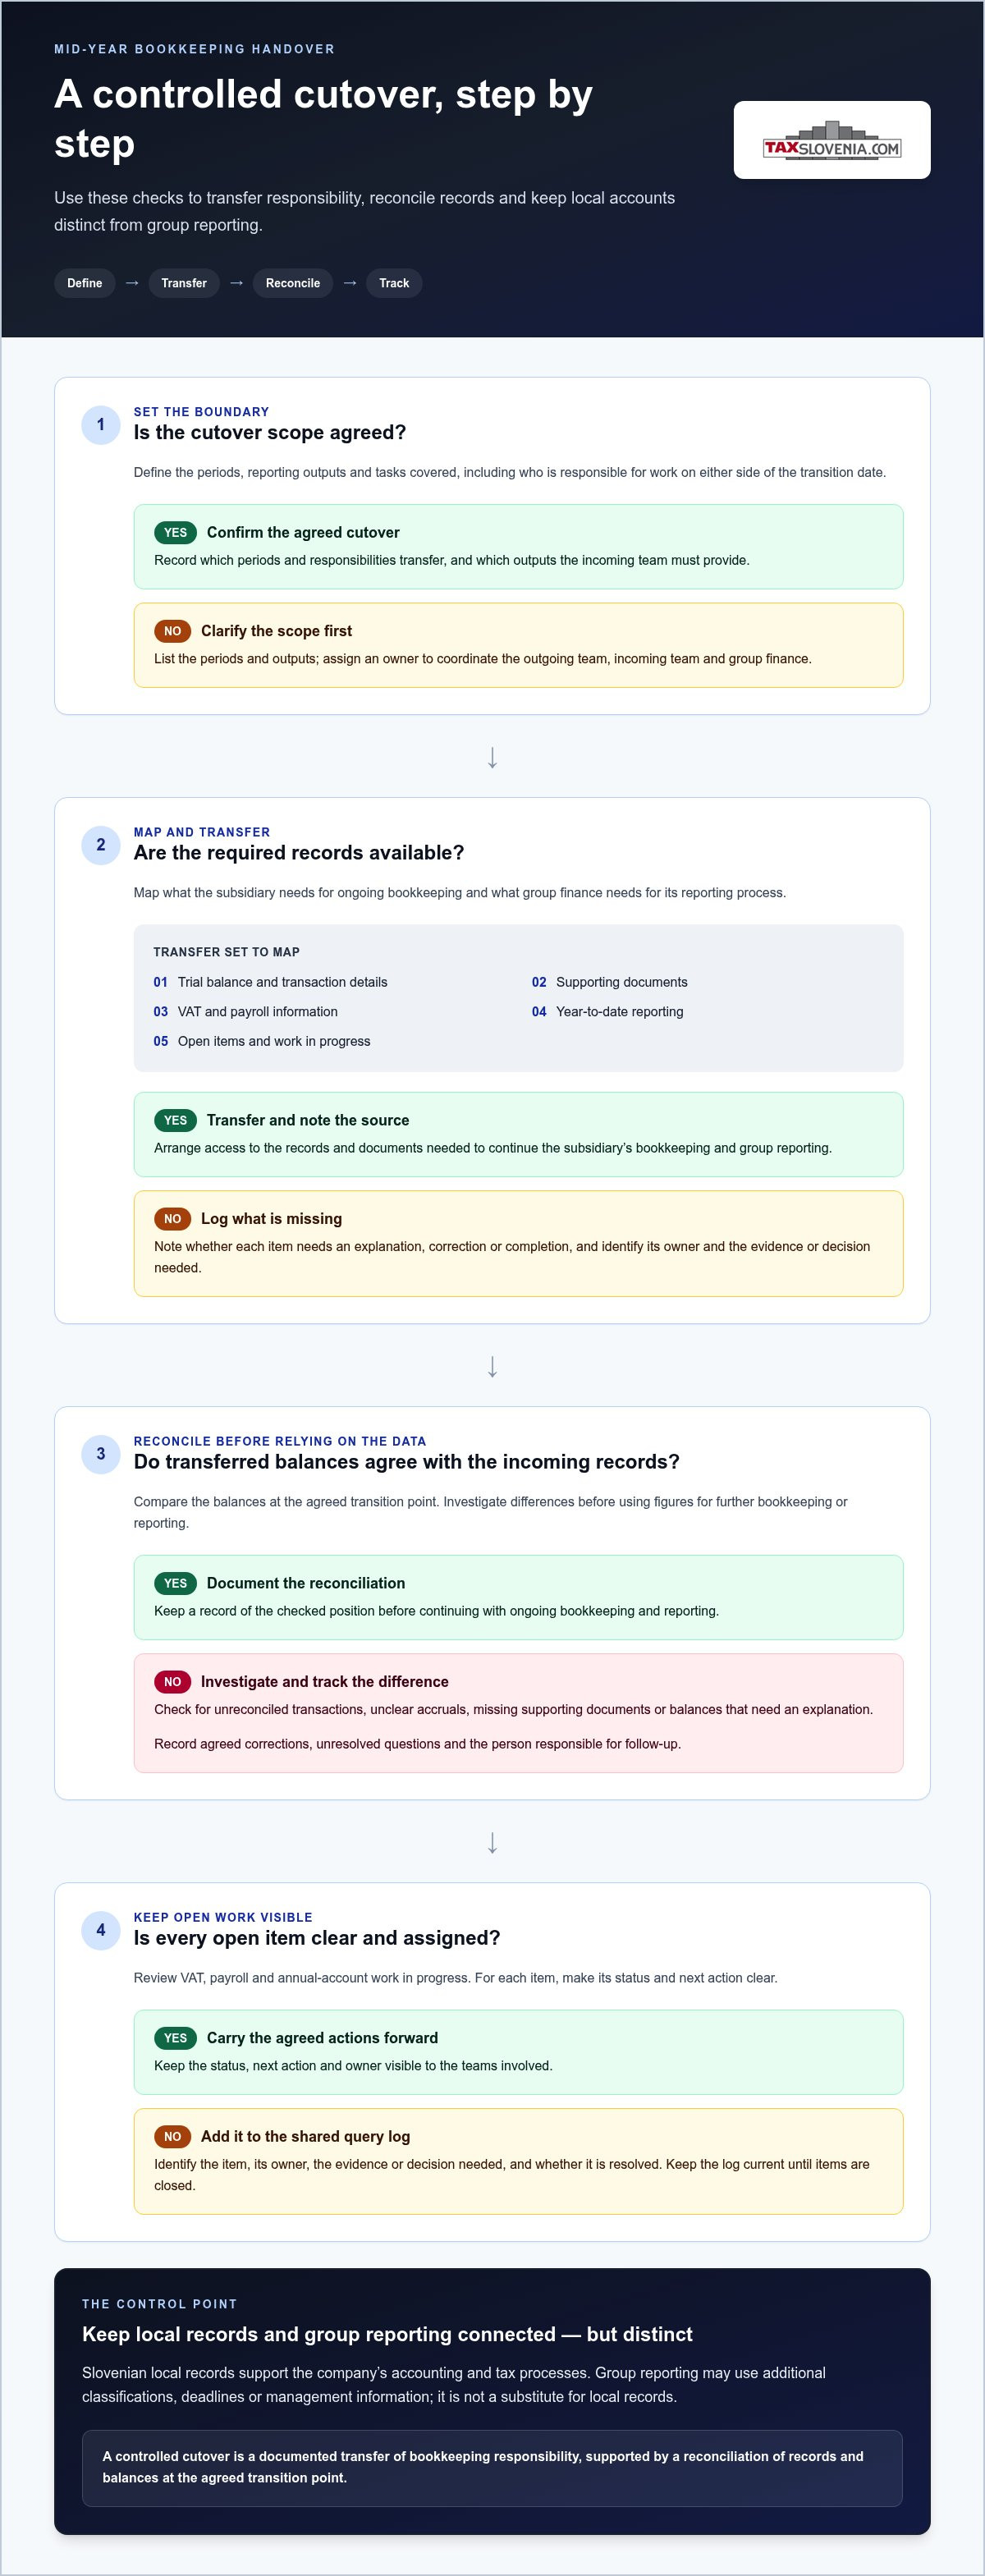
A controlled cutover is a documented transfer of bookkeeping responsibility, supported by a reconciliation of records and balances at the agreed transition point.
- Agree the scope and cutover. Define the periods and tasks covered, including responsibility for work on either side of the transition date.
- Map the records. List the trial balance, transaction details, supporting documents, VAT and payroll information, year-to-date reporting and open items needed by the subsidiary and the group.
- Transfer the data. Arrange access to the necessary records and documents. Note any items that need an explanation, correction or completion.
- Reconcile the position. Compare transferred balances with the incoming records. Check key account balances and investigate differences before using the figures for further bookkeeping or reporting.
- Review and track. Record agreed corrections, unresolved questions and the person responsible for each follow-up. Keep the query log current until the items are closed.
Which handover records and reconciliations need attention?
Map the records required to continue the subsidiary’s bookkeeping, VAT and payroll work, alongside the information needed by group finance in Stuttgart, Munich, Vienna or Switzerland. Check for unreconciled transactions, unclear accruals, missing supporting documents and balances that need an explanation. A shared query log should identify the item, its owner, the evidence or decision needed and whether it is resolved. This gives both teams a traceable link between the local accounts and group reporting.
For a Buchhaltungsübernahme d.o.o. Slowenien unterjähriger Wechsel für Konzerne aus Stuttgart, this process helps coordinate the subsidiary’s records with finance stakeholders across Germany, Austria and Switzerland. TaxSlovenia provides bookkeeping support for companies in Slovenia. Discuss your handover with TaxSlovenia.
How TaxSlovenia can support ongoing accounting after the change
Once the handover is complete, an ongoing process needs to serve both the Slovenian company and the Stuttgart group. TaxSlovenia provides monthly bookkeeping and payroll, as well as annual accounts and statutory filings. These services support the company’s local accounting records and give your group finance team information to coordinate its reporting.
For a Buchhaltungsübernahme d.o.o. Slowenien unterjähriger Wechsel für Konzerne aus Stuttgart, agree how recurring local outputs will connect with the group’s internal processes. Slovenian accounting records and statutory outputs remain distinct from any additional management reporting the parent company requires.
Aligning Slovenian accounting with Stuttgart group reporting
At the start of the engagement, agree the reporting formats, points of contact and recurring information needs. For example, specify the periods used by the group, the supporting information its finance team needs and how questions about local accounting items should be routed. If the group uses internal cost centres, provide the required mapping and name the person who can resolve classification questions. Clear instructions help both teams understand what information is needed and where responsibility sits, without assuming a particular software setup or group policy.
TaxSlovenia’s recurring monthly bookkeeping and payroll fees are charged as monthly packages. Tax and legal advice is billed by the hour or at a fixed fee, while VAT registration and the setup of special regimes are charged as project-based fees. Match the scope of the ongoing arrangement to the bookkeeping, payroll, annual-account and statutory-filing support your Slovenian entity needs, while taking the group’s reporting requirements into account.
For information about bookkeeping support following a provider change, contact TaxSlovenia.
Make the transition a foundation for future coordination
Use the handover to establish how accounting questions will be handled in future. Set clear ownership for decisions, queries and escalation so your Slovenian subsidiary and Stuttgart finance team can respond consistently when reporting requirements or business priorities change.
The Buchhaltungsübernahme d.o.o. Slowenien unterjähriger Wechsel für Konzerne aus Stuttgart is also an opportunity to review how local accounting information supports group decisions. Agree who will revisit reporting expectations and how changes will be communicated. This helps the working arrangement adapt as the business develops.
Contact TaxSlovenia to discuss the bookkeeping transition and ongoing accounting support for your Slovenian d.o.o.
With clear responsibilities and open coordination, you can prepare for the next reporting cycle with a more complete view of local records and group requirements.
Frequently Asked Questions
Can a Slovenian d.o.o. change its bookkeeping provider during the financial year?
Yes. The practical arrangements depend on the existing service agreement and the company’s circumstances. Before setting a start date, review any notice or termination terms, assign responsibility for work already in progress and list the records needed to continue bookkeeping. This helps you plan the transition around the actual work and responsibilities involved.
How do you transfer bookkeeping for a Slovenian subsidiary without losing year-to-date information?
Transfer the accounting trail, not just summary figures. For a Buchhaltungsübernahme d.o.o. Slowenien unterjähriger Wechsel für Konzerne aus Stuttgart, give the incoming team transaction-level records and the supporting evidence needed to understand balances. Keep an accessible copy of the transferred information and record unresolved queries, so later reviews can distinguish established entries from items awaiting clarification.
What should a Stuttgart group prepare before changing its Slovenian d.o.o. accountant?
Prepare the existing engagement terms, relevant internal approval and contact details for the subsidiary and group finance team. Identify group reporting instructions that sit outside the Slovenian entity’s local accounts. For example, if Stuttgart consolidates information using internal cost centres, provide the required mapping and name the person who can answer questions about those classifications.
Will changing bookkeeping providers affect VAT or payroll reporting?
The change of provider does not by itself determine the d.o.o.’s VAT or payroll position. However, an incomplete transfer or unclear division of work can disrupt the information used for reporting. List submissions and payroll periods already handled, work still in progress and the person responsible for each outstanding task. Review continuity in light of the company’s circumstances rather than assuming the provider change alters its underlying responsibilities.
Disclaimer
The information provided in this article is for general informational purposes only and does not constitute tax, legal, accounting or other professional advice. Tax treatment may vary depending on the specific facts and circumstances, and legislation and administrative practice may change over time. Before making any decision or taking any action based on this information, we recommend obtaining professional advice tailored to your individual circumstances.


